Your policy may not be the policy you think you have.
Homeowners insurance in Minnesota has changed a lot in the last few years. Here's what homeowners are running into, in plain English, so you can make informed decisions. Educational only; we don't give legal or insurance advice.
Book a free roof inspection
No cost, no pressure. You get photos of everything we find.
Things homeowners are surprised by.
Every policy is different. These are common changes to look for in your own policy documents, and to ask your agent about.
Roof payment schedules (ACV)
Some policies now pay roofs on actual cash value or a depreciation schedule based on roof age, not full replacement cost. An older roof may be paid a fraction of what it costs to replace.
Percentage deductibles
Some wind/hail deductibles are a percentage of your home's insured value (for example 1–2%), not a flat $1,000. On a $400,000 home, 2% is $8,000.
Cosmetic damage exclusions
Some policies exclude damage that affects appearance but not function, such as dents in metal roofs, gutters or siding.
Reporting time limits
Policies and state rules can limit how long you have to report storm damage. Waiting a season or two can put coverage at risk. Check your policy.
Pre-existing & wear-and-tear
Damage that can't be tied to a specific storm date is often treated as wear and tear, which usually isn't covered.
Non-renewals & roof age rules
Some insurers are requiring roof inspections or declining to renew homes with older roofs.
The longer damage sits, the harder it is to tie to a storm.
Hail damage can take months to show up as a leak. By then, it may be hard to prove which storm caused it, and reporting windows may have closed. That's why we recommend a documented inspection soon after any significant hail or wind event, whether or not you plan to file anything.
- Get a free Hail History Report for your address
- Get a documented roof inspection after big storms
- Read the roof and deductible sections of your policy
- Ask your agent how your roof would be paid today
After a storm: a simple game plan.
Check your history
Run a free Hail History Report for your address.
Get documented
Free forensic inspection with a photo report you keep.
Know your policy
Review your roof, deductible and reporting terms with your agent.
Decide
Repair, replace or wait, with the facts in hand.
Same storm. Same roof. Very different out-of-pocket.
Many Minnesota policies no longer pay full replacement cost on roofs. See how RCV, ACV and roof payment schedules change what you'd pay, with real-number examples.
See the ExamplesIllustrative example only. Your policy, endorsements and insurer determine actual amounts.
Know what hit your home before you make a single call.
Four things we give every homeowner at no cost and with no obligation. Keep them whether or not you hire us.
Storm History Report
A dated record of the hail and severe wind events that crossed your exact address.
- Dates of past hail storms
- Estimated hail size at your property
- When your home was last hit
Forensic Roof Inspection
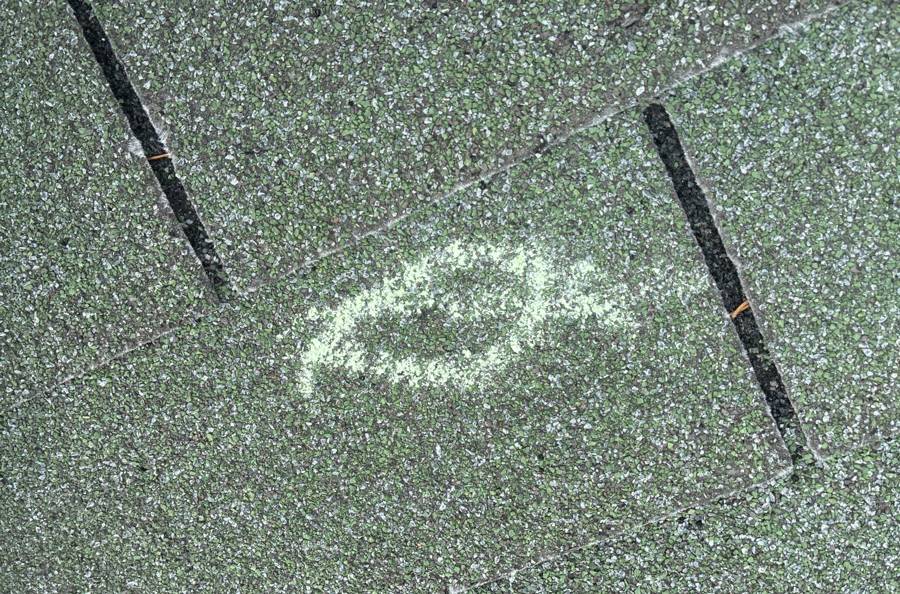
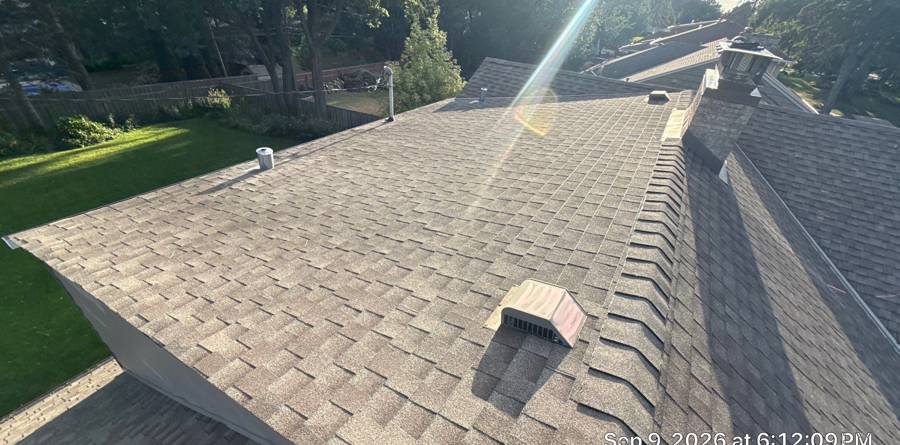
A hands-on inspection of your roof, siding, gutters and soft metals, done to a documentation standard.
- Hail hits chalk-marked and measured
- Test squares and slope-by-slope checks
- Wind creases and lifted shingles
Photo Damage Report
Every finding organized in a photo report that's yours to keep and share with anyone you choose.
- Close-up and wide photos
- Damage labeled by location
- Plain-English summary
Written Estimate
A line-item repair or replacement estimate, so you know the real scope and cost before you decide anything.
- Itemized materials and labor
- Repair vs. replace options
- No pressure, no expiration games
What homeowners say.
My insurance agent called him after we were hit by a storm and he was on site to assess our roof within 5 hours — even with the 2 hour drive to Rochester.
Mike came to do an assessment. He caught concerns others had missed. He was professional and polite but very kind. I would recommend him 100%.
Mike stopped by soon after I contacted Repair King to ask for an estimate on a leaking porch roof. He took the time to inspect the area and explain all the options and give advice for next steps.
Straight answers.
How do I know if hail hit my house?
Start with a free Hail History Report for your address, then get a hands-on inspection. Most hail damage can't be seen from the ground.
What's the difference between ACV and replacement cost?
Replacement cost generally pays what it costs to replace damaged property with new. Actual cash value subtracts depreciation for age and wear. Some policies apply ACV or a payment schedule specifically to roofs. Your declarations page and roof endorsements will say which applies.
What is a percentage deductible?
Instead of a flat dollar amount, the deductible is a percentage of your home's insured value. A 1% deductible on a $350,000 home is $3,500.
Will Repair King tell me whether to file a claim?
No. That's your decision, made with your insurer or agent. We give you a documented inspection and photo report so you have the facts about your roof's condition.
Does it cost anything to get an inspection?
No. Inspections and Hail History Reports are free.
Storm hit? Leak showing up? Let's look at it this week.
Free inspection, photo report, straight answer.